Showing posts with label 股海浮沉. Show all posts

Friday, August 31, 2018

FAJAR (7047) - Q4 2018 Quarter Report - Slam Slam Slam!


FAJAR (7047) released their Q4 result, quite disappointed with it, QoQ and YoY both drop >50%.


Looking into each segment, all are under perform compared to Q4 2017 except construction. FAJAR's revenue are mainly contributed by Construction, Timber and Property Development. however, the segment that contribute the most to it profit margin are Timber & Property Development, and both of this segments are bad. Even the revenue from the Construction sector has improved a lot, but the contribution to the profit margin is significantly lower compare to the 2 key main segments.

Prospect:The only positive point is the management kind of confident that Timber business is coming back, the rest seems like still expect to struggle for a while... what the f.. hahaha

Share price to day had slit ~11%. It had came to my cut loss point, If Monday have no sign of recovery, than i have to cut loss despite the bad performance and the uncertain future profit.


Sunday, August 19, 2018

Hanwell - Aug'18

 
Hanwell announced their Q2'18 report on 10th Aug, below are some highlights captured from the report.

Consumer Business: +4.47% in 2Q18 (+4.22% 1H18) mainly due to higher distribution sales from Malaysia. Distribution in Singapore is actually lower compare to last Q due to close down of the retail shops (how come i not aware this??), actually not much info about Singapore retail market. Growth in Malaysia market is kind of good new, however, there is a risk of RM running weak, so lets see the performance for the next report. Comment on overall consumer business was highlighted as below: Price hike of rice is beginning to stabilize especially from Thailand and Vietnam. Forward purchase planning in this segment will be essential to sustain current gross profits till end of the year. Price hike for both pulp and recycled paper for the paper products has stabilized. However, margins in this sector are under pressure due to retail price increase lagging behind raw materials cost increase. So the blame goes to price of raw material.

Packaging Business: +30.5% in 2Q18 (+24.6% 1H18) nothing special as the growth are expected to be coming from China operation. looks good but need to note of some key point mentioned by Alan:
  1. Singapore’s operating environment is expected to remain challenging for the Packaging business segment with the increase of raw material costs in anticipation of unfavourable exchange fluctuation of SGD against USD and the volatility of raw material prices.
  2. For China's operations of the Packaging business segment, the escalation of trade tension between US and China will impact its export. This will further aggravate the over-capacity of corrugator packaging industry and lead to more intense competition of the industry.
  3. Also in China, the stringent pollution control regulations of China government
  4. The potential of unfavourable exchange fluctuation of RMB against USD will result in increase in raw materials costs.
Notwithstanding this segment will continue to execute its strategy to improve operational efficiencies and further reduce costs diligently. The Packaging business segment is expected to commence the operation of its new production line of Nantong Tat Seng in the fourth quarter of 2018.

While for the financial statement, below are some highlights for me to take as notes:

  • Property, plant and equipment written off was not there last year
  • Inventory is higher, the explanation is last year inventory low due to peak season in Dec'17 - Wah! like that also can!
  • Net cash generated from operating activities is actually lower in 2018 ya!
As summary, Hanwell still running fine with some white spot here and there. The share price never move a lot after this report, so definitely this is an boring counter, also there is where to find a net - net stock. The purpose of investing in Hanwell is to have capital growth, and that should come from the share price movement, so far i still haven't see any solid movement despite they reported kind of "good" result in 2Q. Despite the RM would likely continue to go weaker based on current trend and a lot of uncertainty of the trade war between China and US, overall Hawell still have his business under good control. I will keep Hanwell for awhile until end of the year,

Monday, August 13, 2018

Weekly Review - 0812

The main activity for this week is to dispo my Asian Pay Tv. It is sad but is a must do with the reason that i shared in my previous post. After i dispo the Asian Pay Tv, i quickly SWAP to some other stock. Fajar and Malton are the 2 stocks that quickly take up my capital from the disposition of Asian Pay Tv. Why Fajar and Malton? first of all, this 2 counters were mentioned in the "Rainmakers", well, thanks to the page and i stretch a bit to check out the feasibility to invest in this 2 counters. Together, i put in a fundamental comparison with Ekovest, Destini and WCT as well. Again, the goal is to look for Malaysia MID CAP developers who have good fundamental, good earning capability and reasonable dividend pay out.


Above data captured from 7th Aug (all except Ekovest) to 13 Aug (Ekovest) through investing.com. can see that Fajar and Malton are the top 2. Based on market CAP, WCT is not really the same batch with the rest and i put it in just as a refferance since it is one of my closely monitored counter.

Fajar have a mix business with additional income from Timber, so to be honest, by putting Fajar in the list to compare is really not an apple 2 apple comparison but rather orange and Mandarin orange comparison. As for Malton, it comes with the honer from Pavilion and some good project on hand is definitely some positive point for it. another key reason for selecting this 2 is, they both have the top 2 highest dividend payout based on current price. In view of their trend, both had kind of recover from bottom with >10% recovery liao, enter at this point will be more comfortable for me since the trend shows recovery and not batting on the re bounce.

Fajar
 
 Malton

For the strategy, the capital from Asia Pay Tv will be divided into 2 and invested in Fajar and Malton @ the price of RM 0.495 and RM 0.655 respectively. Any cut loss? based on the trend and EMA, Fajar should cut at 0.485 while Malton should cut at 0.61, anyway, I'm not so certain about the cut loss price at this moment since the Fundamental for this 2 counters are reasonable to hold for mid to long term with current enter price. Both counter will have their quarter result published in Aug'18, so lets see how it goes.
 
Below is my updated portfolio:
 
Key Notes:
  1. Swap from Asia Pay Tv to Fajar and Malton, loss of ~26$ from Asian Pay Tv :(
  2. Singtel reported their latest Quarter result on 8th Aug with drop in revenue, share price impacted immediately since 10th Aug.
  3. Hanwell reported their latest Quarter result on 13th Aug, which is higher than Q2'17, today is the first day the share price reflected the good news. 


Tuesday, August 7, 2018

A Review on Asian Pay Television Trust


APPTV just announced their latest quarter report, such a disapointed result. Infact, it is not totally unexpected, this is what capture from the latest Q-report end 30 Jun 2018:

In constant Taiwan dollars (“NT$”), revenue down 4.1% for the quarter and 4.9% for the half-year as foreign exchange contributed 2.5% negative variance for the quarter and 1.8% for the half-year
  • Basic Cable TV: Down 4.6% for the quarter and 5.6% for the half-year in constant NT$ terms mainly due to lower subscription revenue, driven by marginally lower number of subscribers and ARPU compared to the pcp, and lower revenue generated from channel leasing partially offset by higher airtime advertising sales.
  • Premium Digital Cable TV: Down 10.4% for the quarter and 9.2% for the half-year in constant NT$ terms. Generated predominantly from TBC’s average Premium digital cable TV RGUs each contributing an ARPU of NT$133 per month during the quarter for Premium digital cable TV packages, bundled DVR or DVR-only services.
  • Broadband: Up marginally for the quarter and remained broadly unchanged for the half-year in constant NT$ terms. Generated predominantly from TBC’s average Broadband RGUs each contributing an ARPU of NT$439 per month during the quarter for high-speed Broadband services.
Total operating expenses: Lower operating expenses, mainly due to lower broadcast and production costs, staff costs and other operating expenses.

Below table tell a better story:
In short, the game still on with increase RGUs in Premium digital cable TV but hidden rock shows ARPU for both of the so call potential savior for APTV is not making and real income (claim to be due to spending for promotions and discounted bundled packages that were offered to generate new RGUs and to retain existing RGUs.

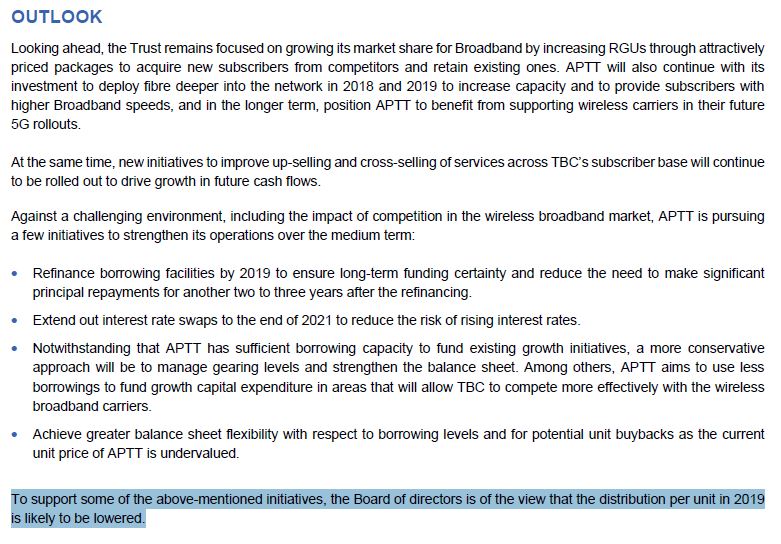
A sad part from the report is below highlighted statment were spotted in the Outlook statement:

==> To support some of the above-mentioned initiatives, the Board of directors is of the view that the distribution per unit in 2019 is likely to be lowered.

My intepretations:
1. The situation is bad, management have no confident to recover the weak performance.
2. DPU lower always not a good thing for me.

A side thought: Do youconfident that APTv can recover the situations by cutting the DPU and with above plan? It all went back to the business that APTv is doing. With that says, i had decided to cut loss at this point, sold off all i have @ 0.40 and take the loss of ~26%. A simple reason, APTv have no longer meet my needs as the future DPU is not secure, so just cut and move on.

I had swap to some Malaysia construction counter. update in next blogging. 

Sunday, July 29, 2018

投资成本


先不说买股票有没有赚,只要你做买卖transection,你就要付佣金了,所以今天心血来潮,想看看我这些年来买股票被投行抽的佣金有多少,就从2012到2018 七月吧。这不包括Contra,是的,我定力不足,时不时会玩Contra。

看到summary了吧?我自己都吓到!!这些是感觉不到的成本!其实,逻辑很奇怪,股市如果我们频密地做买卖,单单被抽的佣金就很可多了,还要自己操做那么高风险的投资产品?
...

有时候你不把东西画出墙是看不到的,好好研究,看定定再买,要不然陪了夫人又折兵啊!

Singtel - 4th Jul'18


Singtel closed at 3.02 yesterday, what a direct flight from ~3.40 to current price. So what drives to this trend? The logic seems works for me, main trigger from May 17: Singtel announced the Q4 and 2018 Final report:
  •  Revenue increased (+4.9%) but the underlying net profit dropped (-7.8%) if exclude the gain from the disposition of NetLink Trust.
  • Revenue increase for all the sector except for the National Phone and International Phone, this 2 consist of a small portion of the revenue @ ~8%, something to note but not big.
  • Operation profit dropped mainly from the result of a decline in Airtel’s India earnings and charges from increased network investments and spectrum.
  • 2018 total Div payout is ~81% (include all the special div). This is good for 2018 but no longer for future where by the Div payout will be fixed at 17.5ct for the next 2 FY. Resume the 60-75% Div payout only by FY21.
  • Expect stable “single digit” profit for next 2 years before Singtel can see anything increase in the profit.
Recent share buyback (actually very tiny if compare to the overall all Cap size of SingTel.):
  • May 17: SGD ~1 mil @ SGD3.42/3.43
  • May28: SGD ~ 0.44mil @ SGD 3.34
Risk:
  • Increase of compaction in Singapore telco market with new players coming in end of this year.
  • India Telco join venture is facing hard fight with new competitor.
  • Invrstment cost.
What Singtel is doing so far (According to the latest annual report):
  • Singtel embarked on a company-wide digital transformation more than five years ago to rebuild our business around data and digital. As digital eroded industry barriers and disrupted old business models, going digital has meant developing strategies that go beyond the context of our telco industry. Instead, we have leveraged our telco assets and customer relationships to develop new businesses such as cyber security, digital marketing and smart city solutions. We have also begun building a digital ecosystem with our associates to aggregate millions of customers across the region. As digital
  • Had revolutionized consumer behavior and company processes, we have also digitalised our core consumer and enterprise businesses.
  • Our new growth initiatives have grown from strength to strength – our digital and ICT businesses now contribute nearly 25% of Group revenue.
The reason i buy in:
  • Share price @ 52 weeks low (S$3.4 at that point of time)
  • Good div pay out and stable track record
  • Singapore blue chip
  • Regional dai kor for Telco
  • Sound solid management (based on the road map and transform seen on Singtel)
Any changes against my reason of purchase?
  • Share price @ 52 weeks low -> No, now even lower... haha
  • Good div pay out and stable track record -> announced fix DY for 17.5ct for next 2 FY and resume in FY21, still acceptable to me.
  • Singapore blue chip -> No change
  • Regional dai kor for Telco -> No change
  • Sound solid management (based on the road map and transform seen on Singtel) -> No key person changes
Conclusion:
  • Hold at this moment in view of Div payout in Aug.
  • Expect small re-bounce after reason heavy sell.
- Temporary have no plan to top up, lets see the share price movement in this few days as well as after the Annual GM on 7/24.

Holding (11th June 2018) - *Throwback

Capital Distribution:
  • 1% Cash
  • 97% Share in SGX
    • 42% in 1 high pay Reit (13.8% DPU)
    • 55% in 2 different Companies
  • Annual div payout based on current PF is ~6.2%.
 Since the first review on 15th May, i had made some changes to my portfolio, the main reason behind is to streamline my portfolio and focus on fewer counter that i'm confident with.

1. Asian Pay Tv:

 I had made a transaction to average down this reit at 0.46c, of cause, that is before it went down to ~0.41c and now come back at weaker momentum. My current avg price is at 0.54c with paper loss of ~19%. To be honest, the situation is ugly, i have to admit that, i'm only looking at the high DPU of this counter (~12.2% at my avg price), other than that, the situations of the company are not that attractive with the high gearing and challenging business environment. 2 key challenges for the company are: the popularity of internet Tv in the future over current cable Tv, and the tax rule changes at Taiwan (increase from 17% to 20% for related business), which had significantly impacted the profit of the company.

Well, the situation is still in mix, as the company have an advantage of 100% owning the hybrid fibre coaxial cable network in their franchise areas of Taiwan (Taoyuan, Hsinchu, Miaoli, TaiZhong), owning this facility have add advantage to the company in the sense of:
  • Building the Fibre cable is a resilient business with high barriers of entry due to high network roll out requirements.
  • Large customer base makes TBC attractive to local content providers; unique commercial arrangement with content providers.
  • Long standing relationship with subscribers; deep understanding of Taiwanese viewers’preference.
 How i look at the situation is: although there will be a hard fight between internet Tv and cable Tv, the high quality internet will need to rely on the broadband, which is backed-up by the hybrid fibre coaxial cable network. So, with regards how bad the fight is, Asian Pay Tv should also get some return from their cable network. A good news is that the broadband business is the only business that seeing growth in the latest quarter, which at least re-leaf my short term worried on this counter.

2. Avi-tech.
 I disposed all my Avi with several reasons:
  • Wth the same DPU at ~5%, Singtel seems to be having more advantage in terms of the share price and the business model.
  • I entered Avi without much advantage of the share price, and the latest Quarter report shows decline in the profit, indicates by the weaker demand of electronic testing. So cutting out this counter at 9% loss and work it out as per the plan.
3. Singtel

 No doubt, Singtel share price declined after they announce the latest quarter report due to the profit are not meeting the market expectation. With the original plan to avrg down at 3.2-3.3 and cut loss at 3.0, i had top up some units at 3.29 (after seeing recovery from 3.24), unfortunately, the share price went back down again recently to 3.23. My average price is now at 3.4 (~5% paper loss), but i have no worried about this counter at all: a blue-chip with share price @ 52 wk low + 5% DPU + good management + Temasek holding... hahaha... This will be my long term game.

4. Hanwell

This is really a boring counter, but i had decided to top up more at 0.23c, it is at net net stock at this price. The company have 2 key businesses: A good growth sector from their paper packaging business, and a stable + solid business sector from their FMCG (rice, toufu, snack and bla bla bla....). There is a lot of potential for the share price, and relatively lower risk due to the good FA.
That is all for the changes in my portfolio, now i have a high DPU Reit (relatively high risk ), a superb bluechip stock and a low risk net net stock, i'm very comfortable with the arrangement. I guess the missing type of counter in my portfolio will be a high growth mid cap stock. lets reserving bullet while continue searching for my last piece of puzzle!

Sunday, June 3, 2018

REIT


今天讲产托,毕竟它占了一半我的portfolio。产托在我的portfolio占了相对大的比例是因为:
  1. 风险比起普通股票相对来得底
  2. 平均股息比普通股票高
  3. 股价对于市场的反应相对迟钝
 
所以,投资了产托就甭想暴涨,当然,暴跌的机率也比较低,总结一下:平均股息高,股价反应慢,有足够时间决定买卖策略。
 
本人比较喜好新加坡的产托,原因是平均利息会比大马产托高,分别大概是 7-8% vs 5-6%。我也发现在新加坡上市的REIT未必一定是在新加坡置产的,在外国置产的有 Lippo Malls (印尼)及 Dasin Retail REIT (中国)等等,可供区域风险管理的选择。
 
好了,那选择REIT的标准呢?其实这个是很个人的,如果新加坡的话,我偏好的产业会是Officec Building 及工业区,大马产托的话我就比较喜欢购物广场,当然还是以个别的股息及财务状况来决定。我在S-REIT Investment Blog 发现他的选REIT标准蛮适合我的,以下是一些参考数据:
 
-> at least 8% yield.
-> Price that is lower than its NAV.
-> Low gearing (if possible)
-> High secured NAV.
 
再来是对现在新加坡和大马产托的看法:
 
新加坡:

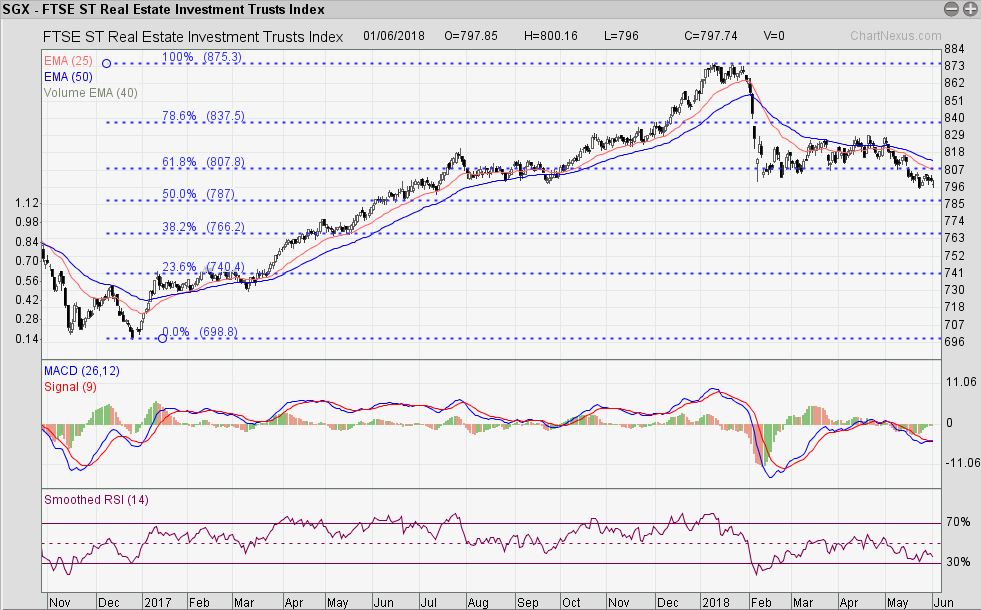
FTSE ST Real Estate Inv Trust Index 打从2016年尾牛了一整年,从701点爬到2018年一月的~874后就往下掉了,现在来到~800点,看来是在下跌趋势中。Phillip Securities 在五月做了统计,市场上笼统数据都显示厂房,仓库的出租率及租金都在下降,多家产托最新几个季度的业绩都下降了,唯一比较明朗的是拥有High techpark的,这看得出是响应了新加坡政府的smart nation program。有兴趣的话可以找找哪家产托是着重于出租high techpark的,可能还可以收一收。此外,新加坡还有一些信托是归类在REIT以下的,有机会再分享。
 
大马:
 
REIT指数在今年三四月探底~856点后,现在已经回升到~950区域了,那是一口气往上爬的,接下来因该会来个小调整,然后再往上爬。配合大马换政府的不确定性,产托成了避险股被推了一轮,在加上新政府废除GST,让很多的产托的股价再继续冲到了今天的950点,尤其是广场型的。当然,我只看到retail的产托有比较明朗的前景,至于办公室产托在这一轮的上涨后能不能维持后续就有所保留了。
 
好啦,我手上有一只新加坡的REIT,不过不是传统的,内人有两只大马的Retail REIT,下一篇可以看看。。

Monday, May 28, 2018

Singtel (SGX: Z74)


基本面:

新加坡电信老大。和其他两家电信(StarHub, M1)比较的话,SingTel 在新加坡的mobile market share有49%,不过只有30%的盈利是来自新加坡,另外22%和48%来自澳洲与其他亚太地区的电信投资(摘自2017年报),总结是她的风险管理我个人觉得一流,毕竟新加坡竞争强,市场小,新加坡以外的机会比较多。

盈利方面是很稳定的,派息也很规律。前景的话,SingTel 在几年前就已经部署进军digitalisation sector,大概就是big data, cloud, cyber securities, smart city 等等,盼了几年,最近终于开始供应盈利了,这也是为什么他们不急于react to M1在新加坡的数据削价战,人家志不在此啊。总的来说,Singtel的管理方式是倾向于稳健的风险管理,加上长远的投资(比如三年前的策略性进军digitalisation sector)。

最大股东就是新加坡政府咯,淡马锡52%,外资14%,新加坡本地市场大概12%。所以股价变化不大是可以理解的。

数据的话蛮不错的(from Investing.com up to 2017 annual data)

- 双位数ROI: 14.6%
- GM: 52%
- OM: 27.4%
- NPM: 32% (投资贡献盈利比较多)
- D to E ratio: 32%

SingTel 的 PE (TTM) 大概在10,比起StarHub 和M1 (16&12)是比较低的。如果考虑到规模问题,那就要和Axiata 比较了,Axiata PE 在56,所以也不用看了。哈哈。

技术面:

52周新低在 S$ 3.30, 今天S$ 3.41。图表的话,自从一八年三月创了新低后,底部价在慢慢往上升,还需要几个月时间看会不会是上升趋势。下一道上升阻力大概在S$ 3.54 和 S$ 3.65。

策略:

增持:S$ 3.20 - S$ 3.30
止损:S$ 3.10 (-10%)

SingTel 会是我尝试巴哥和芒哥的另一种投资策略,即是以合理价(不是低估价)买入优质股。我在五月初买入,价钱在S$ 3.41,目前占portfolio的二十出趴。止损点放在S$ 3.10,原因是因为她的周息率其实很稳定,在5%左右,况且S$ 3.30已经是五年新低了,感觉不太可能到这个价位,除非新加坡经济倒退五年?哈哈。名牌股就收就一点咯。

Saturday, May 19, 2018

HANWELL HOLDINGS LIMITED (恒威集团 SGX:DM0)


*基本面:生意是FMCG起家的,为了加强盈利,恒威也投资在纸箱制造。

1) FMCG (Fast Moving Consumer Goods), 就是卖基本需求的。这样的生意好处是很stable,当然,盈利也不高。他卖什么呢?
  • 在新加坡卖米的,人家的米还是Top Seller in Singapore “Popular proprietary brands include Royal Umbrella rice, Golden Peony rice, Gitangkim rice, Okome rice, Taj Ponni rice, Harmuni rice and oil, Golden Circle oil and Soyalite oil.”
  • 也卖Tissue,年报是这样写的 “Beautex was named in the Singapore Book of Records as the first to launch a complete range of premium and economical three-ply tissue products.”
  • 还卖豆腐,“Besides specialising in soya bean-based products such as tofu and tau kwa, Fortune Food is also the pioneer in introducing Sobe, Singapore’s first fresh, pasteurised soya milk, to the local market in 1995.”
  • 还有零食,“Socma specialises in 4 main categories: confectionery, snacks, grocery items and beverages. Some of the household brands that Socma exclusively distributes include Mentos, Chupa Chups, Smint, Fruitella, Tao Kae Noi, Tai Sun, Supernut, Mazola, Soyalite, Golden Circle, Harmuni, Indomie and Jia Duo Bao(formerly called Wong Lo Kat).”他的零食基本上是卖在马来西亚。
2) 纸箱制造 (Tat Seng Packaging Group Ltd,介绍是这样写的:

Tat Seng is one of the leading manufacturers of corrugated paper packaging products listed on the mainboard of the Singapore Stock Exchange. With operations in Singapore, Suzhou, Nantong, Hefei and Tianjin in China, Tat Seng serves the packaging needs of various industries in Singapore and China by supplying a range of corrugated paper packaging products of different configurations and sizes.

Its customers include Multi-National Corporations and local manufacturers in food and beverage industry, electronics and electrical industry, plastic and metal stamping industry, pharmaceutical and chemical industry as well as the printing, publishers and converting industry. Over the years, Tat Seng has progressed through continuous improvement and has been maintaining a stronghold in the marketplace.

Tat Seng's key products include corrugated paper boards, corrugated paper cartons, die-cut boxes, assembly cartons and heavy duty corrugated paper products.

*基本面:业绩 (2014-2017年报)
  • Gross margin TTM 22.58%
  • Operating margin TTM 5.49%
  • Net Profit margin TTM 4.51%
  • Return on Investment TTM 7.48%
  • Quick Ratio MRQ 1.83
  • Current Ratio MRQ 2.07
  • LT Debt to Equity MRQ 0.08%
  • Total Debt to Equity MRQ 22.1%
盈利每年增长,除了2015掉一点。纸箱制造占65%,其他的是FMCG。个人觉得管理层风险和盈利管控都很好,唯一比较失色的是DY很低,管理层好像不是很想回馈小股东。

根据Q118季报,CPS (Cash per Share)有大概有 S$ 0.71.
这是一支 net net stock,股价已经来到52周新底了,前景不错,只是老板有点吝啬,DYU只有~1%。刚读完巴非特的Ground Rule,就买入少少看看。

*策略:
 
1) 第一批:买入价 0.225新币 (Done);
2) 第二批:低于0.22 / 0.21 (Pending).
3) 不止损
4) 长线 两年

Sunday, July 23, 2017

无题。。。


It has been ~2 years.. and a short update is i had returned all the gain from 2008 - 2013 to the market. Spending the pass few months to figure out what is the problem, and the conclusion is: i had made too many transection without proper assessment.

Saturday, August 9, 2014

Is SUPERMAX a case of 狼来了??

Last Friday, i decided to clear all my SUPERMAX @ 2.2+. walau! so fast scare liao!! hahaha. few reason make me take this move, however, my move is not because of panic market, it is because of signal that i learn from Mr Hu, and i try to apply it, since i still have some pocket money from it. This are the reasons why i buy SUPERMAX before hand:

1. SUPERMAX is having the lowest PE at this moment with about 11, TG is running around 15 and KOSSAN is 18.

2. TG and KOSSAN start to move a bit already and left only SUPERMAX. Yesterday it closes at flat but there is a spike up to 2.2+ during lunch time.

3. Weekly volume starts to pick up in pass 3 weeks, 10 days average price start to trend up.

and my original TP for SUPERMAX is RM2.56.


I decided to clear it one shot on Friday due to:

1. Continuously 4 days OHCL (Open High Close Low).
2. Volume Shrinked significantly.
3. Politic standpoint of SUPERMAX.
4. Global Event which is getting worst off.

From the trend point of view, i buy in with volume pick up, and i have to sell it when volume shrink together with share price trended down continuously with 10 days average line also start to flip down on Friday. I would beleive the continuous red for SUPERMAX is due to over brought in the solid green bar on Monday, however, even for the gunner and 投机客,they also need to wait for T3 to force sell, so when i see the 1st red after the green couple with long upper needle line and high volume, i pretty much confirm that the big fish is disposing SUPERMX hardly, not difficult to know that one of the giant fish is the EPF, this will link to point number 3 later. The volume and share price movement for subsequent three days further makes me almost 100% sure that the up trend for SUPERMX had been interrupted.

From point number 3, after i entered SUPERMAX, i did read quite a numbers of journal regarding glove industry and SUPERMAX, and one of the point i pick up is the SUPERMAX is anti government, hahahaha. Although i haven't see any latest new on how the management team of SUPERMAX criticize the gov, the latest article that SUPERMAX complaining the government are as below, and from what EPF had been doing all the while (Keep dispose and dispose), it is really a company that hard to get the support from GOV, at least this is what i feel.

http://biz.sinchew.com.my/node/91328?tid=6
...

速柏瑪執行主席兼董事經理鄭金森
政策須利永續成長

速柏瑪(SUPERMX,7106,主板工業產品組)執行主席兼董事經理拿督斯里鄭金森表示,政府上調電費16%,全部人都受到影響,政府准許一家賺錢企業上調電費,實是令人覺得這可是件瘋狂的事!

同樣的,若是膠手套業者在沒有合理原因上調產品價格,他們的客戶也一樣質疑他們是否瘋了。

國家能源是家賺錢企業,政府還要上調電費及增加大家的成本。希望政府收到的額外收入善加利用。同時,讓更多業者參與再生能源領域,擁有平等的參與,以應對電費起價。

除了電力能源外,膠手套業者的其他經營風險,包括外匯波動及原料成本走高等。若要膠手套業持續成長,政府的政策可說是扮演舉足輕重的角色。
政府進行減赤行動實是無可厚非,惟不應該將減赤優先事項放在削減津貼方面。

電費漲打擊競爭力

鄭金森指出,上調電費,這不應該是政府首要考量,反而應該積極減低不必要的開銷。政府應該抑制不必要的開銷及弊端。

鄭金森指出,政府反而是先行處理政府出現的任何批漏與弱點、減少貪污、改善政府效率等領域,而不是一味加重各行業成本負擔而打擊競爭力。

公用事業甚至獨立發電廠業者取得數10億令吉盈利,但還是需要調漲電費?不僅企業,中低收入群也將面對電費上調衝擊。

本地膠手套行業不時針對市場變化而做出改變,不過,他認為政府也一樣需要做出改變,防止政府的錯誤,包括國家能源必須提昇它的效率,因為其他國家膠手套業者的能源成本,比大馬便宜及更具競爭力,特別是國家能源是壟斷領域。

目前本地膠手套行業每年的營業額達到約300億令吉,佔據全球膠手套市場逾60%,目前最重要的問題,是本地膠手套行業將從目前情況下走向何方?
他認為,膠手套業者知道如何經營它們本身的業務,不過,若是缺乏一個有利製造業者的經營環境,業者是很難繼續擁有永續的成長。

他指出,政府實施的政策非常重要,包括吸引人才回歸措施。特別是目前的價格都在揚升,政府有必要提供獎掖,包括新興行業地位及在油氣領域的優惠等。

本地膠手套行業每年為國家帶來逾100億令吉淨收入,有鋻於此,政府的政策有必要有利經營環境,以便吸引業者繼續投資甚至再投資。政府有必要有長期計劃,以助業者與其他國家競爭。
Lastly, with the recent dip on share market (for it, it is more like an over react on the market due to the fire call on Iraq from Obama). with the unstable global situation, i think it is hard to gain the confident of the investor to put their money in the share market at least for a short while, even I'm the investor that obey the Mr Market, i will also keep my money in other counter for now at least.

The quarter report for SUPERMAX will be out this month, and i quite confident that it will be a good one. However, i do believe that the share price on last Monday had reacted to the good result + the Ebola effect.

With the cash on hand, i will swap it to another counter either WEIDA or MARCO on Monday depends on the situation.

Sunday, August 3, 2014

MUDAJAYA India Power Plan Operation Timeline Get Pushed Out AGAIN???


Found this in INVESTALKS by spy008

http://www.investalks.com/forum/forum.php?mod=viewthread&tid=2700&extra=&page=51

I called Mudajaya Investor Relation on 30th July 2014 2pm++,
I have spent about 16 mins speaking with their IR, Mr. Benjamin.

I asked about the status of few projects, and these are the answers I got (I couldn't confirm all the information given to me are correct, but everything I wrote here are exactly what he meant):

1) Regarding the India Power Plant, their latest revised date for firing the 1st Power Plant is by end of 3rd Quarter (end of September). If 1st plant launched successfully, other remaining will start launching 1 by 1 (each takes 1 quarter).

**This is not a good sign **

2) Mudajaya is the "technical support" in civil for the power plant 3B that has been awarded to 1MDB - Mitsui Joint Venture. However, the size of the project has not been revealed and still undergo "tendering"/government's approval.

(This project has high chance and might be announce "soon", depending on 1MDB & Government.)

3)  He said that the Joint Venture with Mulpha is still going on, Mulpha has bought the land. However, they might "wait and see" the market. The launching might be after GST...


He said that the property market is quite quiet now...

(I was totally speechless when heard this =.='')


 4) When I asked about the 0 orderbook;

He said that he agreed that Mudajaya has 0 orderbook for quite a period of time. This is because the company strategy is rather not to get the job if the job has low profit margin/loss, as it is a waste of manpower & resources. He gave example of BinaPuri only getting 1% of profit margin. He said that Mudajaya has high profit margin among construction company. He also explained that Mudajaya can easily win several projects, for example, UiTM (Couldn't remember the name, I know is a University/College) but they chose not to tender the project as it was not profitable.

5) He further explained that the company is not sitting duck/ doing nothing while there was 0 orderbook. The CEO has been aggressively venturing into renewable energy in Indonesia/ Philippines to create recurring income.

To sum up, Mudajaya will still having tough time in the next 6 months...


+++++++++++++++++++++++++

Looks like the share price will still heading South for some time, wandering what the MUDAJAYA menagement is doing??

Ebola fears... SUPERMAX up 19 sen.

The Star Online:
http://www.thestar.com.my/Business/Business-News/2014/08/01/Glove-makers-advance-on-Ebola-fears/

KUALA LUMPUR: Glove-makers bucked the weaker broad market on Friday as investors saw buying opportunities amid expectations of a surge demand in gloves following the outbreak of Ebola virus in Africa.

At 11.12am, Supermax was up 14 sen to RM2.31, Kossan added nine sen to RM4.10 while Adventa gained eight sen to RM1.12 and Top Glove edged up seven sen to RM4.70.
The FBM KLCI fell 4.85 points to 1,866.51. Turnover was 864.71 million shares valued at RM564.67mil. Losers beat gainers 527 to 179 while 276 counters were unchanged.
Reuters reported Sierra Leone has declared a state of emergency and called in troops to quarantine Ebola victims, joining neighbouring Liberia in imposing controls as the death toll from the outbreak of the virus hit 729 in West Africa.

The World Health Organisation said it would launch a US$100mil response plan on Friday during a meeting with the affected nations in Guinea. It is in urgent talks with donors and international agencies to send more medical staff and resources to the region, it said.

The WHO on Thursday reported 57 new deaths in the four days to July 27 in Guinea, Liberia, Sierra Leone and Nigeria, raising the death toll to 729. It said the number of Ebola cases had topped 1,300.

++++++++++++++++++++++++++++

病毒肆虐 美元升值 手套股回春 涨势难测
财经张欣豪

http://www.orientaldaily.com.my/index.php?option=com_k2&view=item&id=130084:&Itemid=198

(吉隆坡1日讯)西非埃博拉(又称伊波拉)病情肆虐,加上美元兑令吉匯率升值,刺激年初表现低迷的手套股,大马4大手套公司股价今天纷纷上扬,惟分析员普遍相信这只是短暂的投机活动所致,手套股涨势能否持还要胥视疫情的发展。       
隨著西非国家塞拉利昂昨日宣布进入紧急状態,其邻国利比里亚也情况严重,马股手套股在今天受到投资者追捧,顶级手套(Topglov,7113,主板工业股)、高產尼品(Kossan,7153,主板工业股)以及贺特佳(Harta,5168,主板工业股)分別上扬14仙或3.024%、8仙或1.995%以及4仙或0.605%,其中顶级手套和高產尼品分別成为全场第11和第19大上升股。
至于速柏玛(Supermx,7106,主板工业股)则是4大手套股中,表现最佳,全天共起19仙或8.756%,至2.36令吉,成为全场第9大上升股。
针对手套股在逆市中上扬,接受《东方財经》询问的分析员普遍指出,埃博拉事件使到投资者重新注意上半年表现低迷的手套股,但今日升势相信只是基於投机活动,这些手套股的股价涨势能否持续,仍须视疫情接下来的发展而定。
不愿具名的研究主管以及分析员认为,埃博拉病情若成为跨区域或跨洲疫情,势必成为手套领域强大的催化因素,甚至带动一股手套股大牛市;但若病情受到控制,相信投机活动將会迅速结束。埃博拉病毒是一种人传人的病毒,若扩散情况严重,將大大增加全球手套需求。
安联星展研究分析员表示,短期內不看好手套领域,尤其是在目前令吉兑美元呈上升趋势以及供应过剩的情况下。此外,明年的竞爭相信会更激烈。
无论如何,他认为,手套领域长期依然正面,毕竟手套股的基本面和估值仍属合理。
他指出,本次针对埃博拉病情的升势並不稳定,必须视接下来的疫情,才能决定这股上升势头能否延续。
肯纳格投行分析员表示,今天的手套股升势除了因为埃博拉病情,今天美元兑令吉大幅升值也是其中一个因素。截止今天下午尾盘,美元兑令吉相比昨天上升了0.62%,至3.2174令吉。
肯纳格投行看好手套领域
肯纳格投行分析员对手套领域较为乐观,认为手套股目前已被低估,其中供应过剩的消息已被严重放大。
他指出,目前大马手套公司的丁月青手套都处於满负荷產能,近期都在扩展新生產线,以迎合市场不断增加的需求。
手套股上半年一直表现低迷,本次病毒危机或成为一个强大的催化因素。加上手套市场的需求一直有稳健成长,肯纳格投行看好目前被低估的手套领域。
年头至今,速柏玛跌14.8%;顶级手套滑落15.28%;高尼產品跌5.32%;贺特佳跌8.02%。
安联星展研究及肯纳格投行分析员都认为,速柏玛今天表现最佳,是因为之前的股价表现最不好,且股价较便宜。
安联星展研究的手套首选股是高產尼品,目標价4.90令吉;肯纳格投行对手套领域的投资评级为「超越大市」,首选股贺特佳,目標价7.48令吉.


++++++++++++++++++++++++++++++

Up to last Friday, Supermax had up ~7.8% from by purchasing price, this was not expected for short terms. wish the disaster will end soon..

Saturday, July 26, 2014

牛市熊市三步曲, My Final Portfolio Optimization

 Captured from 牛市熊市三步曲.
http://money.softbath.net/stock/articles/bear-bull.htm

...................

牛市第二期
  市場中開始受利好消息刺激,部份股票股價開始慢慢持續或反覆向上,投資者也漸漸開始對經濟前境有所期待,雖然開始時市場成交沒有明顯的熱鬧,但伴隨各大公司公佈的業績轉好令投資者回復信心而開始入市慢慢變得熱鬧,對後市更開始樂觀。

牛市第三期
  到達這個時期,經濟環境已開始起飛,投資市場也到達非常熱鬧的階段,就好像2006年香港股票市場般幾乎全民階股、新股必賺般熱鬧雀躍,到這時候,市場也會對各種消息變得非常敏感或,一點消息也會造成炒作活動,部份非專業投資者更可能會跟隨各種消息而盲目追捧參與投資炒作活動令市場波動,值得注意是經濟環境將由好漸漸轉壞時由於不易察覺可能對投資者做成損失。

 
熊市第一期
  熊市的開始往往在牛市第三期經濟最熱鬧的期間默默開始,在牛市第三期間,各種經濟指數和部份股票股價可能都已沖跛新高,各投資者也沉迷在賺錢的貪念中,雖然市場看來仍然一片熱鬧,但已存在過熱的危險性,熊市初來臨時一般並不明顯,就是因為並不明顯的關係,市場中的炒作仍然活躍,只是開始有少許反幅波動,能在這時放出手上股票還是可以有利可圖,當部份投資者已察覺熊市來到時,開始相斷沽出股票,市場將一步一步下跌,如投資者已明顯地察覺熊市己來到而加快沽出手中股票,更可能做成恐慌性拋售,這一擊的力量可令市場迅速大幅下跌而造成嚴重損失,而且事前不易發覺。


A few activities i had made in last few days to fine tune my portfolio based on current status (牛市第三期). Did realize that in pass 1 month or 2, a lot of cash rich counter had move up in spike says 20 - 50%, this told me that the last phase of bull market is almost here, once all these cash rich counters had raised, the final group of penny lousy counter will be the last push for the bull. I really don't like to put a lot of capital in the penny lousy stock, so i have to catch up with the last round of raise of cash rich company, once take profit from there then i will start to back off liao!! this is my target, help me to achieve it and not been over taken by the greedy inside me :P

Alright, the changes that i had made in pass 1 week is to focus on shifted some of my counter to those under estimate counter although it is very hard to find one today. firstly i have to SWAP with my current counter, FIAMMA and LATITUD had been taken off from my portfolio with 2 reasons:

1. Both had came down 3% (my stop loss point) from my enter price, so to follow rules, i will need to sale it. (FIAMMA - enter 2.12, now 2.07, LATITUD - enter 3.09, now 2.99).

2. Lesser and lesser momentum to move up after 1 round of increase in share price. Its unlike UliCorp, this 2 counter seems to have a hard time to move up further and if look at the future on Latitud, the shutdown in Vietnam will definitely impact her revenue for upcoming quarter, thus, before it can recover, the phase 3 bull should be passed. where else for FIAMMA, the reason i bot in is his stable business (home use electric equit and property), but looking at the market, targeting for stable business just seem not right for me if i want to increase my gain in stock market now.

In fact, both are good counters , just i decided to invest together with the Mr market. By selling of this 2 counters, i swap to MARCO and WEIDA.

Why MARCO?

1. Cash rich "2013年财报注 明公司拥有4千1百50万的现金"
2. High DY.
3. The Business: do you use Casio product??
4. The share price is not really moving yet
5. PE ~12. not so attractive but still fair.
6. Top 30 share holders holds about 54% of total share.

http://klse.i3investor.com/blogs/kianweiaritcles/55457.jsp

Why WEIDA?

1. Cash rich company after sold off the plantation business
2. The share price is not really moving yet
3. low PE and under value.

A lot of discussion on this counter at I3investors can have a look on this guys.
http://klse.i3investor.com/servlets/stk/nb/7111.jsp

below is the latest portfolio with the % of my capital:

Local:
18% WEIDA @ 1.86 (cash rich, super under value and not yet move at the day i buy)
10% MACRO @ 0.17 (cash rich, not yet move with high DY)
15% MUDAJAYA @ 2.58 (close to 25 week low, profit coming on it way)
19% SUPERMX @ 2.17 (close to 52 wk low, recovered from production issue, increase profit)

Foreign:
24% CHINAPOWR @ 2.9 HKD (Blue Chip, main power supply in China)

will the 4 local counter to be the last piece of 遗珠? lets see. From now on, i will stop any buy in activities for other counter, the only thing that i might do is to swap my CHINAPOWER/MARCO to WEIDA, out of these counter WEIDA, might be the safest bet :), bottom line! make profit! but how to decide when to run?? hahahaha... there will be some way to know that and i will try to provide it in this round of market.


Saturday, July 12, 2014

Supermax @ 2.16

Enter Supermax @ 2.16

 
I had been eying the glove counter for few weeks, comparing few glove makers, below is some of my though on timing:
1. Supermax is having the lowest PE at this moment with about 11, TG is running around 15 and KOSSAN is 18.
2. TG and KOSSAN start to move a bit already and left only Supermax. Yesterday it closes at flat but there is a spike up to 2.2+ during lunch time.
3. Weekly volume starts to pick up in pass 3 weeks, 10 days average price start to trend up.

*From TradeSignum
 
Business point of view, global glove demand is always in increasing trend but it is slow and steady kind of uptrend, unless there is a global illness issue like SARS kind of thing, else i don't think the market will react actively with this kind of silent growth, thus i do not expect the share price to shot up spiky unless it get goreng, but long term, it should be trend up to reflect the actual value of the company. from 2013 annual report, the CEO Stanley Thai had mentioned that Supermax had set up a sales office and store in US Chicago, this move is encouraging as US is the major market of medical glove. On top of this, on June 2014, Stanley also highlight that that company is moving into RUSSIA and other ASIAN counter as they are seeing more business opportunity here. it is obvious that the company is aggressively improving the market share and looking for new business opportunity. In negative side, China is also aggressively expanding their market share in glove industry, this remain a competitive challenge to the company with the potential risk of oversupply. We see this effect in pass one year on all Malaysia glove makers.

*From I3invetor page
 
As for the accounting figure of Supermax, latest 2 quarters is running with low revenue mainly due to the output shortage caused by the fire of her manufacturing site in Alor Gajah, the manufacturing line is expected to be fully recovered by Sept/Oct 14. Thus, it should be any issue there. Debt wise, obviously Supermax is not a cash rich company for now, however, with the business outlook that they have, it is acceptable to me if they reserve the money for business expending. 
 
*From 2013 Supermx Annual Report
 
Share holder wise, top 3 share holders had taken up about 42% of total share, and top 30 share holders had consumed up to 65% of total share. EPF is the 3rd largest share holder but its only takes about 6.25%. Top 2 shares holder is Mr and Ms Stanley Thai. Recently EPF is keep on selling but the company is keep on buying back, from here, i can feel that the company is quite confident with their future especially the key share holder.
 
 
*From Q1-2014 Supermx Quarter Report
 
*From 2013 Supermx Annual Report
 
"On the dividend front, similarly to FYE2012, the Company has paid out an interim 4% tax exempt dividend for FYE2013 and the Board has proposed a final 6% tax exempt dividend which is subject to shareholders’ approval at the upcoming Annual General Meeting. This is largely in line with our aim to pay out 30% of Profit after Tax (increased from 20% prior to FY2012) in order to further reward our loyal and supportive shareholders". -- Supermax 2013 Annual Report
The Company also aiming of giving 30% of profit after tax as dividend to the share holder. From here, it seems like Supermax is not a aggressive 成长股 anymore, well, it still a good news for me anyway.

Based on above brief review, my plan is to invest 30% of my capital in Supermax with buy in 3 steps $2.16, $2.20, $2.24. cut loss at $2.05 (5%). i set the cut loss at 5% is because for me, Supermax is already hitting the bottom, if it went down further at current market, which mean she have some background issue that not known by me. while for accumulation, i buy in 3 stage with 3% increase in share price so that i can make sure i riding on the correct trend and secure my capital if anything went wrong tomorrow.

With the recovery of the production line, i expect the EPS for 2014 to be around 16cent (3.9 for 1st and 2nd Q due to pending production line recovery and 4.7 for Q3 and Q4 with full recovery of the production line) and with the fair PE of 16 in glove industry, the TP for Supermax should be around $2.56. This is equal to around 16% return of my investment. However, I’m going to apply止损不止赚like what i did on ULICORP, the decision of sell will be based on volume and share price momentum. :)

I know it is not responsible to write a lot here and ask you to buy on your own risk, but i still want to say that, buy on your own risk :)
 

Thursday, July 10, 2014

Settle all my ULI @ 1.68

I had disposed all my Ulicorp share on hand since yesterday with average price of 1.68, total gain from the counter is about 52%...LOL

This is today's disposition

 I decided to dispo all the ULI now with 2 reason:

1. The volume become lower and lower for pass 1-2 weeks, thus the share price have no more momentum to move up further. Indeed, this is normal after it climb from 1.09 until now..

2. The 5 days average line had make the U turn to move down and 10 days average price start to be flat. Although this is just an alarm signal, but with the uncertain of the BNM meeting result, I decided to cabut.

3. Market is a bit high now, and BNM had announced to OPR, it's time to stand a side and decide my next move.

Alright, after disposing ULI, my main counter in my portfolio remain as CHINA POWER (35%), MUDAJYA and FIAMMA (18% each). Cash vs share is 30/70.. Looks a bit high... Haha

I will be looking for any chance to reduce my holding of FIAMMA and swap to MUDJYA, comparing this 2 counter, MUDJYA haven't really move while FIAMMA had move a lot in pass few weeks, and the power generator business is more interesting as compare to property development and home use electric business, LOL!

Stock under my rada is WEIDA, AEON and glove company (haven't decide).. Might do some swapping here.. BUT!! Before that, let's stand aside and look at what the market do tomorrow with super big dip of US stock which is happening now and the impact of OPR increase... 


Sunday, July 6, 2014

My Stock Investment Review for 2014 1st Half (P2)


Alright! what happen to IOIPG and Sunway?? i was entering Sunway on Nov 2013 and IOIPG on Feb 2014 after it IPO.


For Sunway, i had been buying it due to super low PE and price dip when gov announced the cancellation of DBS scheme. After holding for 8 months i decided to fully dispose it from my profile with 1 time dividend paid to me as well. Why??

 
SUNWAY had hit $2.23 once and trended down for the pass 1 month, what i see here is the impact of not enough volume momentum and the upcoming GST impact to propety sector is an unknown for SUNWAY, although in general, it should be able to hold the resistance of all this impact. my original TP for SUNWAY is $2.40, but as what i mention above, i would rather swap my capital to other counter which might have clearer view for next 1-2 years. In short term, it should be benifit by the upcoming hospital project, Inskandar project (launching soon) and the new theme park near Subang Jaya. Long term, it should be positive, but i'm not expecting something like >50% return on this counter, what ia greddy man :)

For IOIPG, i bot in this counter after 1 month of her IPO when her share price drop from high of $3.5 to $2.5. The reason i invest on this counter is the capital size and the reputation, however, i was over look by her PE @ $2.75 which is around 11. IOIPG having quite a number of property investment overseas, by looking at the property market in other country, it expose additional risk for IOIPG with the exchange rate and the uncertainty. Local project wise, it have some land @ JB and KL, but i do not see any selling point of IOIP property as compare to others. i decided to dispo it @ lower price after if come down @ high at hitting my 3% cut loss limit, why 3% for IOIPG? it is simple, the future is uncertain for property sector and IOIPG also exposing herself with the risk of overseas investment, with PE >11, i don’t think there will be high flying performance in near future for IOIPG. What i joke in my investment history, another example of taking action without proper thinking :).

Now, let’s talk about my investment strategy for 2nd half of 2014. It is simple:

1. Target to have 4-5 counters holding
2. Avoid property sector,
3. Looking for dark horse
4. Cash vs stock ratio of 20:80.

Buy and selling plan:


1. 10% for high potential counter and 3% for high risk high return counter.
2. Capital invested in a single counter should be more than 20% of my capital.
3. Buy in stage with additional entrance in every 3% price increase (until hit the 20% limit).
4. Start selling the counter when 10 days average price line start to turn down with no volume support.
5. Counter with PE more than 10, max PE = 12.


Now, i have ULICORP, LATITUD, FIAMMA, MUDAJAYA from KLSE.

ULI - Bot in early this year when PE = 7 at price of $1.09. This post is a bit late and now it is running at $1.66 on Friday, it is closed to double up d and the good thing is i learn from UMWOG and TITIJAYA that not to cut gain, so i still holding it, it is currently the 2nd largest counter in my profile. FA for ULI no needs to mention, it is solid, ULI involved in Investment, Cable support systems, and Electrical lighting and fittings, a pretty stable business. Since the increase in the price is likely due to goreng, so i will continue to hold it or start to sell in stage when: 1. No big volume >9mil in next 2 weeks, 10 days average price start to turn downward, PE between 15 - 18.

MUDAJAYA - I just started to collect this counter @ 2.51 with PE around 8, eyeing at her India power plant project. The share price still not moving a lot, so i will use this counter to try out my "3% enter once" strategy on this stock, see how it goes. Long term wise, it had committed with 75 mil profit per annual from the India projects, in short, i do not see any bad things on this counter unless her project delay again. Things to take note also on her profit earning on recent 2 quarters, it is low and i will need to find out why.

FIAMMA - I had complete my "3% enter once" on this counter with average price of $2.13 with PE of 8.+. FIAMMA is selling the home used electricity equipment and now it starts to enter the property market, while the key i chose this counter is the stable business of house use electric equip but with the property sector in the counter, i have no way but need to be more sensitive to any property related news in Malaysia. it is a highly recommended stop by 糊涂 and you can take a look on his comprehensive analysis on this counter on his blog page.

LATITUD - Furniture manufacturer, bot in this counter @ average price of $3.09, PE more then 10. i came to know this counter during the 越南排华事件, There is a lot of detail review and FA result comments of this counter in I3investor page. In short, this is a 龙头股, 3rd Q is a traditional low performance time for furniture sector but she is still performing, part of it is because of the privatize of her sub company, but excluding that, this is also an earning quarter and its better than last year. The overall business performance is also better then competitor. This counter should be performing soon after Vietnam case. However, this is a buy based on follow. Thus, I’m getting a 8% capital on it only, although i quite confident on its performance.
 

My Stock Investment Review for 2014 1st Half (P1)

Had been away for half a year... now here is the check point for pass 6 months of my progress, below is the profile from Dec 2013 - June 2014.

 
To date, some good profit for 2014, main things happen on my profile are Disposing some of the key stock like Fitters to Feb 2014 after shot up ~17% and SWAP to UMWOG and TITIJAYA.
 
Some lesson learn here, for UMWOG and TITIJAYA, they are IPO when i brought it and seems like it had been disposed too early. currently both are running at $4.22 and  $2.49 each any my previous enter and exit price are $3.16/$3.87 for UMWOG and $1.49/$1.79 for TITIJAYA. this had translate to about 10% and 48% less profit if i hold until today. the lesson learn is don't simply let go some potential counter, but how i know will it continue to go up or will drop back to my buying price? Recently, i found to known an investment book and the trick is: "cut loss don't cut gain", on the upcoming counter, my cut loss point was set at 2 level, which is -3% and -10%, why there are two standard? well, it is depends on which counter i invested and the potential of the counter. And how i decided to start taking profit? i will based on 2-3 weeks price vs Vol movement to decide, which mean whenever the counter is having hard time to move up and the vol continue to see low, also not expect any new catalyst from market, then i will start to sell in stage. this will be my investment strategy for the 2nd half of the year ! yeah!
 
Next is the item in red which is RSAWIT, ICAP, and IGBREIT. this 3 is really a fail for me in year 2014, it is purely follow wind kind of buying, although the capital that i put inside was not as huge as others, but it is a loss!
 
I’m buying RSAWIT in the early of the year when we are talking about the kelapa sawit price will be the theme for 2014. why RSAWIT and not THPlant, CEPAT and others? Well, i just simply chose one and bot in just to hope to catch up the 投机 (for me). so this is the result, when i found another good counter, i have no enough capital to invest but to cut loss on 投机股.. 悲剧啊..even look at today, RSAWIT are just not performing, i believe it is mainly due to the young trees on this company that is not making the good profit on it as compare to other plantation counter, maybe this is not her year, but who knows what will happen in few years later?
ICAP and IGBREIT is a good counter, but again, i'm selling it to SWAP to other counter and the enter price for ICAP is a bit higher even that she is priced below her NTA for an investment company. This counter that applied 价值投资 on her invested target; ideally, this is an investment company that is using the same investment style like Berkshire Hathaway.  but the different is the share price is always below its NTA -40%, and she do not give any dividend until 2014, i think the CEO cannot tahan already but to give the very first dividend to share holder else he will start to loss the main pool of investor, dude 50% in 5 years! how many investor in Malaysia can hold for so long just for 50% and without dividend??!! In summary, this is a good counter but not serves the needs of Asian market, face the reality man, we are only human! hahaha. 

ICAP (2009 - 2014)
 

IGBREIT, again, i have not holding power...... it is now at $1.22, with ~4% gain from my enter price if i hold it until now. This is a good example of investing with not having a clear investment strategy. at today’s market, it kind of like the 3rd phase of bull market and i should be targeting some under value stock to catch up the last train before the bull market is here, IGBREIT definitely not in the list as this is more towards conservative investment, so once i realize that IGBREIT is not my cup of tea, I’m cutting it directly and pay a $50 study fee... damn! it is equal to a set of sushi!
Next, I’m going to talk about IOIPG and SUNWAY, also talk about my latest holding including SG stock... :) 

Tuesday, December 3, 2013

Bot in SUNWAY @ $2.66 Last Week, 3rdQ report looks good

Over pass week, i had bot in another 20 lots of SUNWAY @ 2.66, i'm holding 80lots now with average proce of 2.70. SUNWAY had announced the 3rd Q report:
 
Not so bad is general.
 
Yesterday price dip hardly but today recover, guest i should get some yesterday but i not dare to catch more on falling knife :). still looking good infuture, lets hold it.