看了8year前辈的一些关于Malaysia房产泡沫的文章,让我感慨现在新山房地产的情况
http://8yearsblog.blogspot.com/2012/08/2013.html
柔佛屋价在近几年真的是涨了很多,但也太快了吧?!两年前我买下了现在住的屋子,当时我是以RM450k买下来的,Clustter SemiD 四年屋龄再加上家私,在2010上旬时的这个价位算一点点偏高了,但是由于地点漂亮,保安系统好,所以就买下来了。
在短短的两年里,今天我这里的屋价以同样的配套计算,现在的市价是介于RM700k-800k之间,涨了进50%,而同一区的新屋,clustter semiD都已经在RM680k起跳了。这屋价的涨潮依小弟的看法是酱的:自从经济复苏后,马劳也开始增加了,居住于新山的马劳也越来越多,自然,这些人的购买力也增加了,但是新山还有一大部分的人是不在新国工作的,所以这两个不同income source的购买力差异也越来越大。反观新山的发展,不管你走到哪里,你都会看到一大片正在发展的组屋condo。这些发展是冲着马劳及新国人来的。
很奇怪的事发生了,每每你到新屋推介会,那些屋子都会被一抢而空,现在500k的condo一天就卖完了,是真的那么好卖吗??先不管是发展商欺骗我们还是真有其事,屋子销售得那么快的原因肯定的是有很大的投机成分。不管是马劳,新国人,还是本地新山人,大家明显地都看好新山的房地产,大家都觉得还有屋价上升的空间,大家都觉得欣欣向荣 :)
再来看看,新山不像KL或槟城,新山有很大一片土地,说不上寸土是金,屋价上涨得快,以小弟的愚见看来,很大成分是for投资。如果是投资那就来算算吧,先别挑排屋,排屋不容易出租,就看condo吧:
价钱:
一间RM500k的两房式condo, 给了10%头期,每个月还得供接近两千,那一间租金可要在RM2000或以上。。不便宜。。
市场:
1。 本地人?本地人肯定租不起,租得起的也很少,要是本地人租的起,那他因该买得起,何必租呢?
2。 马劳?同样的道理,要是租的起,那他因该买得起,如果说不是长住,那在新加坡租房间更划算。进出新加坡很辛苦的。
3。新国人?可能有少数会跟你买起来,那就很幸运了。
投资竞争:
不必多说了,你想到的人家也想到,以现在一扫而空的情况来看,同一栋楼不懂有几间在等着出租。
总的来说,现在新山的屋价太贵了,如果你要买来住那还好,如果买来投资可能会有蛮高的风险,不是怕你供不起,而是一旦你卖或租不出,你还得按时出钱保养它,不然要卖时也没价钱。很多人都会说propety不会贬值,那是对的,除非你买在合理价。那什么是合理价呢?如果你是新山人,有空开车去Bukit Indah, 2nd link, Permas, Setia Indah, Setia Tropika看看,如果你觉得供求平衡,那当下的价钱就是合理价了,如果有人告诉你新加坡,吉隆坡,槟城屋价更高,那是应该的,因为他们是他们,我们是新山 :)
House Price index: http://www.globalpropertyguide.com/Asia/malaysia/Price-History
Sunday, January 6, 2013

Saturday, January 5, 2013
Reason of 加码 FITTERS
Found a post on CARI regarding FITTERS, not so old but also not new, just to share:
+++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++
投資致富 2012-12-10 11:25
芙蓉讀者問:
輝德控股(FITTERS,9318,主板貿服組)前景如何?我早前以每張5仙,買進20萬張輝德控股WA(FITTERS-WA,9318WA,憑單),若全面轉換這批憑單,虧損幾率會有多大?因為我擔心當每個投資者都進行轉換,賣壓會導致轉換成本上升,最終母股會跌破58仙嗎?
答:
輝德截至9月30日首9個月淨利增長18.13%至1千754萬4千令吉,受惠於防火配備及建築原料銷售上漲。雖然該公司一直以來都取得盈利成長,不過卻沒有受到市場太大的關注。
該公司早前與貿易風種植(TWSPLNT,6327,主板種植組)聯營投資綠色提煉廠解決方案活動,將提煉廠排出的污水和棕果渣用於發電和生產纖維。這符合其商業經營模式,除了透過纖維貿易營造經常性收入,也藉此增加收入基礎,相信上述投資項目每年可捎來150萬令吉淨利。
分析員認為輝德攫獲的綠色提煉廠解決方案合約,只能從2013財政年開始顯現盈利效益,並看好該公司未來將宣佈更多類似投資項目,以吸引機構投資者的目光。
綠色提煉廠業務料佔2013財年7%盈利貢獻,但2014年可激增至29%,至2015年更達41%。該公司整體表現不錯,分析員給予其1令吉零5仙至1令吉15仙合理價,不過若缺乏催化劑,股價短期或難有大突破。 (good to catch now :P)
另外,談到憑單轉換問題,輝德控股WA已從11月8日起暫停交易,並在11月28日除牌。以53仙轉換價及你買進的每張憑單5仙計,總成本只有58仙,顯著低於母股約64.5仙。兩者的價差為6.5仙,若乘上手中的20萬張憑單,則可在轉換期限內賺取1萬3千令吉,惟前提是母股仍企於64.5仙水平,而上週五止,每股只處61仙水平,未來盈虧仍胥視母股前景。(星洲日報/投資致富‧投資問診室)
+++++++++++++++++++++++++++++++++++++++++++++++
So, the mother seem to be more attractive to me compare to the WA, even though it is not applicable now, i more interested in the comment of the future earning.
Digging more into the annual report to check out the performance again, as in my previous post, the performance of this stock is consider fare, however, I'm interested to look into more on the company performance during 2007/2008 and 2009 to check out how did she perform during financial crisis, well, this is what i found:


Summary:
1. Company is making profit for pass 10 years, non of the year is making loss.
2. EPS & profit is fluctuating, but still performing at average during 2008/2009 period.
3. Revenue increase in recent 5 years, latest rolling 4 quarters shows slight drop in revenue (404,607) as compare to 2011 but profit is higher then 2011 with rolling 4Q ended at 24,668 (EPS ~11sen)
4. historical gearing looks healthy and well below 0pt5. just a bit concern on the operating cash flow over total asset, it was at -ve on year 2011.
5. ROE not really stable but still +ve.
From business point of view, it is the leader in providing integrated fire protection and prevention solutions as a “one-stop” fire protection specialist. In mid of 2011, the company start to expend into the renewable energy & green palm oil mill, property development and construction engineering which is still a good move from my point of view (anyhow you can only make consistent money with concurring the fire protection market in Malaysia, to growth the company, i think this is a good move).
looking at the top 30 share holder list, they are holding up to ~70% of the share at 2011, the liquidity of share in the market is quite low if it is still in the same status today. Also that the company still carry out quite heavy of share buy back in this year and recently, not sure this is good or bad but at lease this shows that the share holder are still confident on the business (given it to maintain the share price or to accumulate the share)
Good thing is it is not a hot stock and i don't think the market is focusing on this counter, current price at 0.61sen with PE at ~8.7, not super cheap but it has been traded at 2 years lowest price now. current CPO price is pretty low, and by the time the CPO price recover, i would expect the company will be making profit from the green energy division.
FITTERS was introduced by SAM, together with the same time frame, he had also buy in some other stock, however, I only intrested in FITTERS mainly due to what was discussed above. I'm currently holding FITTERS with less then 20pst of my capitial, i'm going to try to swap some of my warrant to FITTERS and make it to about 30pst of my capital, this will be my 1st step to change my invesment from heavy warrant to heavy mother :P
- Just a 2 sense from me :)
+++++++++++++++++++++++++++++++++++++++++++++++++++++++++++++
投資致富 2012-12-10 11:25
芙蓉讀者問:
輝德控股(FITTERS,9318,主板貿服組)前景如何?我早前以每張5仙,買進20萬張輝德控股WA(FITTERS-WA,9318WA,憑單),若全面轉換這批憑單,虧損幾率會有多大?因為我擔心當每個投資者都進行轉換,賣壓會導致轉換成本上升,最終母股會跌破58仙嗎?
答:
輝德截至9月30日首9個月淨利增長18.13%至1千754萬4千令吉,受惠於防火配備及建築原料銷售上漲。雖然該公司一直以來都取得盈利成長,不過卻沒有受到市場太大的關注。
該公司早前與貿易風種植(TWSPLNT,6327,主板種植組)聯營投資綠色提煉廠解決方案活動,將提煉廠排出的污水和棕果渣用於發電和生產纖維。這符合其商業經營模式,除了透過纖維貿易營造經常性收入,也藉此增加收入基礎,相信上述投資項目每年可捎來150萬令吉淨利。
分析員認為輝德攫獲的綠色提煉廠解決方案合約,只能從2013財政年開始顯現盈利效益,並看好該公司未來將宣佈更多類似投資項目,以吸引機構投資者的目光。
綠色提煉廠業務料佔2013財年7%盈利貢獻,但2014年可激增至29%,至2015年更達41%。該公司整體表現不錯,分析員給予其1令吉零5仙至1令吉15仙合理價,不過若缺乏催化劑,股價短期或難有大突破。 (good to catch now :P)
另外,談到憑單轉換問題,輝德控股WA已從11月8日起暫停交易,並在11月28日除牌。以53仙轉換價及你買進的每張憑單5仙計,總成本只有58仙,顯著低於母股約64.5仙。兩者的價差為6.5仙,若乘上手中的20萬張憑單,則可在轉換期限內賺取1萬3千令吉,惟前提是母股仍企於64.5仙水平,而上週五止,每股只處61仙水平,未來盈虧仍胥視母股前景。(星洲日報/投資致富‧投資問診室)
+++++++++++++++++++++++++++++++++++++++++++++++
So, the mother seem to be more attractive to me compare to the WA, even though it is not applicable now, i more interested in the comment of the future earning.
Digging more into the annual report to check out the performance again, as in my previous post, the performance of this stock is consider fare, however, I'm interested to look into more on the company performance during 2007/2008 and 2009 to check out how did she perform during financial crisis, well, this is what i found:
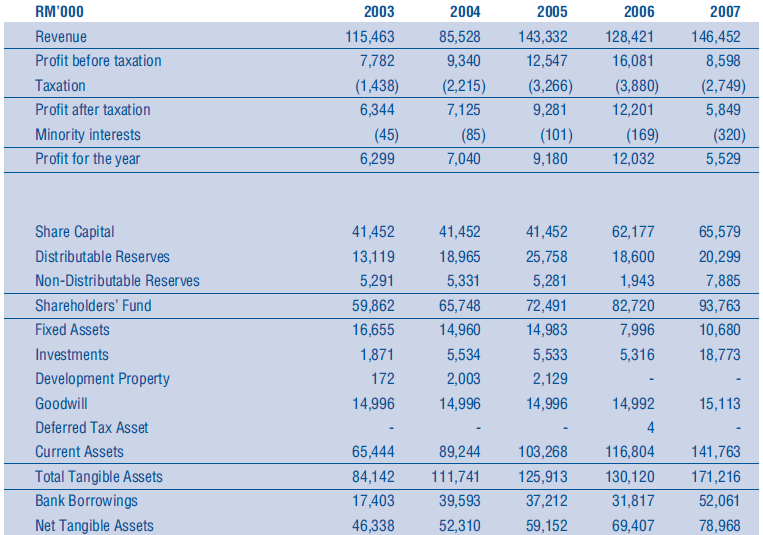


Summary:
1. Company is making profit for pass 10 years, non of the year is making loss.
2. EPS & profit is fluctuating, but still performing at average during 2008/2009 period.
3. Revenue increase in recent 5 years, latest rolling 4 quarters shows slight drop in revenue (404,607) as compare to 2011 but profit is higher then 2011 with rolling 4Q ended at 24,668 (EPS ~11sen)
4. historical gearing looks healthy and well below 0pt5. just a bit concern on the operating cash flow over total asset, it was at -ve on year 2011.
5. ROE not really stable but still +ve.
From business point of view, it is the leader in providing integrated fire protection and prevention solutions as a “one-stop” fire protection specialist. In mid of 2011, the company start to expend into the renewable energy & green palm oil mill, property development and construction engineering which is still a good move from my point of view (anyhow you can only make consistent money with concurring the fire protection market in Malaysia, to growth the company, i think this is a good move).
looking at the top 30 share holder list, they are holding up to ~70% of the share at 2011, the liquidity of share in the market is quite low if it is still in the same status today. Also that the company still carry out quite heavy of share buy back in this year and recently, not sure this is good or bad but at lease this shows that the share holder are still confident on the business (given it to maintain the share price or to accumulate the share)
Good thing is it is not a hot stock and i don't think the market is focusing on this counter, current price at 0.61sen with PE at ~8.7, not super cheap but it has been traded at 2 years lowest price now. current CPO price is pretty low, and by the time the CPO price recover, i would expect the company will be making profit from the green energy division.
FITTERS was introduced by SAM, together with the same time frame, he had also buy in some other stock, however, I only intrested in FITTERS mainly due to what was discussed above. I'm currently holding FITTERS with less then 20pst of my capitial, i'm going to try to swap some of my warrant to FITTERS and make it to about 30pst of my capital, this will be my 1st step to change my invesment from heavy warrant to heavy mother :P
- Just a 2 sense from me :)
妈咪孕二月
进入第七个礼拜了。。你妈咪又要去为你照相了,很对不起,爹地每次都不能陪妈咪去,要上班挣奶粉钱啦,哈哈,妈咪要周日去,因为人比较少,所以爹地就不能去了。。

虽然还看不清楚宝贝你长什么样,但Ah Bee你好像变大了哦!!妈咪告诉爹地说医生让她听你的心跳!爹地半信半疑,你的小心脏已经开始工作了? 哈哈, 我的宝贝你很健康哦!
这个月你妈咪蛮辛苦的,她肚子开始涨风了,由于你的appartment越来越大,把妈咪的胃和肠往上推,所以她时常会打嗝和放屁,肚子好不舒服哦。此外,你妈咪的胃口也变了,以前她超爱吃的面粉稞,现在一点都不想吃,还只喜欢吃apolo layer cake,你妈咪说是因为宝贝你不喜欢,哈哈,所以整个月下来她什么也吃不下,但又不可以不吃,怕你饿到。我们都搞不懂你爱吃什么。为了让你有足够的营养,爹地买了Ammum给妈咪喝,但你妈咪说喝久了很腻,不过没法啦,谁叫你是她的心肝宝贝,她还是乖乖地喝。
这时的妈咪特别懒惰!每天躺在沙发上很累酱,所以爹地答应了她从现在起妈咪不用做家务了,爹地会做完全部家务直到你出生 :) (其实爹地想请女佣的,不过因为懒惰找,所以到现在还是自己做。。)
虽然你妈咪很懒惰酱,但她还是超厉害的,尽然还带你出远门去旅行呢!!那是你第一次坐飞机,还去了印尼,那是她的公司旅行啦,你还算乖,没让她在出门时太辛苦。。
在这个月里,你长得很快,而妈咪开始担心害喜的状况越来越严重,注意哦,他还没开始呕吐哦 :)
妈咪孕一月
想了许久,还是决定把这一份惊喜记下来,2012年10月21号,你妈咪心血来潮拿了验孕棒去test,突然她静悄悄地站在楼梯口然后对爹地说:“Dear,两条线喔”,Ops!那是我们第一次认识你哦,哈哈,爹地开心到不知所措,赶忙冲出买了第二支棒棒要妈咪再验一遍。。。。
第二天妈咪一个人就去妇产科看医生了,证实了你的存在,哈哈,看看你,虽然只有一颗豆那么大,但我们是感觉到你的存在的,欢迎你哦!

你妈咪看了你生平第一张照片后,很专业地算一算,然后告诉爹地说,唔,你应该是九月尾就报到了,哈哈,很Pro酱。。。
我们决定先保密,只告诉了你阿姨和外公婆,阿公阿嬷就两个星期后才被通知,不要让那么多人知道你的到来,怕你烦嘛 :)
第一个月你妈咪还很正常,爹地除了让她吃医生吩咐的药之外,也买了一堆燕窝让妈咪补,还买了一本胎教书,像字典酱厚!要学学当爸爸妈妈了。。

听人家讲如果在你还小小的时候就让你听音乐,你以后会很乖很聪明哦,爹地妈咪就上网download了一堆胎教音乐,在你小小时睡觉前就让你听Mozart的音乐,哈哈,反而是我们睡得很香呢。。
爹地很期待你的第二张个人照哦。。。
Tuesday, January 1, 2013
沉静的两年
我回来啦!!沉静了两年,我人生中发生了很多事,买了房,结了婚,在加上频密的出国公干,我竟然荒废了Blogspot, 哈哈。。Update一下status, 两年来,起起伏伏,在2012年年尾,我好像发现了一些心得。。。我还是不适合频密地交易。。看看以下我的Record:

还是写英文比较方便,虽然是Broken English...hahaha
Review the performance for last 2 years (July 2010 - Dec 2012), although i still have a net gain of ~8%, but this is just like putting my money in the FD!! WTF!! and what i observes from this history is the gain can only comes with long holding time + low/ fair enter price, look at FAVCO, BOC, and Puncak!! average PE at that time is ~4-5! solid company with consistance gain!
How about those i sell with loss? common is i'm not confident to these company and i sold them out each time i hear any bad news, to check back again whether what is the performance of these stock, lets look at it one by one.
Sealink:
EPS continue drop from 2008 - 2011, with roling 4 Quater result, looks like 2012 EPS continue to reduce to 2.58, this mean profit continuously drop for 6 years, while overall market recover in 2010 but the earning of sealink do not follow, i cut loss at RM0.60 with the net loss of 17% :( what a bad buy in move... should see the earning shrink across 2008 to the time i buy in.
FAVCO:
EPS continue growth from 2008 even up to this year, PE when i bot should be ~5-6, now is ~7 :) shere price stod at 1.65 now, too bad i do not have holding power, else gain is ~85%.
SCOMILA:
This burger, performance is really not stable, some more got loss on 2010 & 2011, 2012 roling 4Q still net loss with EPS at -12. although latest 3 quarter it start to recover, but overall, the company is not consistant. short term play is still able to make profit, the LA is now at ~35sen and 1X higher then my buying price, but appearantly i'm not the kind of person that able to pick the gain from this stock, haha..
BJCORP:
This is a big company, but the CEO reputation is not good, the profit also marginal and seeing loss at 2009. lets see why i buy this stock (luckly i do record :P)

Catching chance?! predict future?? haha.. Now this is not a good reason to buy in:
1. Gain still not stable along the time, EPS droping, so it is not a good way to predict the future of the company with not so excellent history data.
2. PE high when the time i buy, it is at ~11. current price is ~50cts, PE ~8
I dispo all at RM1.04, how lucky am i ?!!
HUNZPTY-WB:
This stock looks good in earning,continue increase in profit since 2008, too bad that i'm buying the WB previously, current PE is ~2, Maybe this can be one of the counter that worth to invest. KIV KIV :)
BOC:
This is the stock that teach me a lot, bot in by following SAM and doing so study after that, 4th largest Bank in China, one of the China bank that have more investment in the global market. Price deep to <2 .5=".5" 2008="2008" 2010="2010" 3.4hkd="3.4hkd" and="and" at="at" back="back" bad="bad" boc="boc" brought="brought" buy="buy" crisist.="crisist." current="current" dip="dip" do="do" drop="drop" due="due" euro="euro" even="even" finance="finance" future="future" gainning="gainning" haha..="haha.." have="have" holding="holding" i="i" in="in" increasing="increasing" is="is" it="it" mainly="mainly" market="market" nbsp="nbsp" near="near" not="not" p="p" pe="pe" power="power" price="price" some="some" that="that" the="the" time="time" to="to" too="too" when="when" will="will" with="with" yearly="yearly">
TAMBUN and KSL:
Tambun is a newbee to the main board, KSL is a stable company, both of them is a fair counter, KSL profit up up down down, but still no loss, not bad, Tambun have less history data, need KIV, tambun is now with PE ~9, higher then my buying price.
Overall, with the bad trading history in this 2 years, the conclusion i have is that
1. I'm not suitable to use the "low buy high sold" method, i do not have a full time analysis on the stock and full time monitoring the stock price, thus not suitable to catch the best price.
2. Warrent is not suitable for me, if i have no time to monitor the share price, mean i might need to hold the stock for some time, holding the monther vs warrent, looks like mother is more confortable, of cause, blue chip warrent can be consider.
Current holding stock are YTLPOWR-WB, PJDEV-WC, HAPSENG-WA and FITTER
YTLPOWR, is a cash rick company, with PE ~9, cattching the WB seems more reasonable for me.
PJDEV-WC, this is highest paper loss for my combi as of now. this is a fair counter, my WC might be buying at higher price, for now i can only hold.
HAPSENG-WA, this is also a fair company, marginal paper loss, current PE at ~9, hold for a while.
FITTER, PE at 8.5, also a fair company. hold and see.
Looking at current holding, 75% is warrent?! hmm... my target for 2013 is to swap from warrent to mother stock... :)
Coming up stock selection will be focus at Mother stock, low PE, continueous earning.
Saturday, July 17, 2010
古老的致富秘笈
這則巴比倫最有錢人的故事,看似簡單平常,但在8000年前巴比倫人已經懂得理財致富之道,這些原則到現在一樣可以適用。
巴比倫最有錢的人叫做阿卡德,本是擔任雕刻陶磚工作,有一天,一位有錢人歐格尼斯來向他訂購一塊刻有法律條文的陶磚,阿卡德唯一的條件是歐格尼斯要告訴他致富的秘訣。
完成工作後,歐格尼斯告訴阿卡德:“財富就像樹一樣,從一粒微小的種耔開始成長,第一筆你存下來的錢就是財富成長的種籽,不管賺多麼少,一定要存下十分之一。”
一年後,當歐格尼斯再來的時候,阿卡德很驕傲的說,他確實照他的方法作了,歐格尼斯就問:“那存下來的錢,你如何使用呢?”
阿卡德說:“我把它給了磚匠阿盧瑪,因為他要到遠地買回菲利人稀有的珠寶,當他回來時,我們將把珠寶賣很高的價格,然後平分這些錢。”
歐格尼斯責罵說:“只有傻子才會這麼做,為甚麼買珠寶要信任磚匠的話呢?你的存款已經泡湯了!年輕人,你把財富的樹連根都拔掉了,下次你買珠寶應該去請教珠寶商,買羊毛去請教羊毛商,別和外行人做生意!”
果然,磚匠阿魯瑪被菲利人騙了,買回來的是不值錢的玻璃。
第二年,歐格尼斯再來的時候,阿卡德告訴他:“我把存下來的錢借給鐵匠去買青銅原料,然後他每四個月付我一次租金。”
歐格尼斯說:“很好,那你如何使用賺來的租金呢?”
阿卡德說:“我拿來吃一頓豐富大餐,並買一件漂亮的衣服,我還計劃買一頭驢子來騎。”
歐格尼斯笑了,他說:“你把存下的錢所衍生的子息吃掉了,你如何期望他們以及他們的子孫能再為你工作,賺更多的錢?”
又過了二年,歐格尼斯問阿卡德:“你是否達到夢想中的財富?”
阿卡德說:“還沒有,但是我已存下了一些錢,然後錢滾錢,錢又滾錢。”
歐格尼斯說:“你已學會了致富的秘訣。首先你學會了從賺來的錢省下錢,其次你學會了向內行的人請教意見,最後你學會了如何讓錢為你工作,使錢賺錢。你已學會如何獲得財富,保持財富,運用財富。”.
巴比倫五大金科定律
這則古老的智慧當中,蘊含著金錢的五大金科定律:
金錢的第一定律:
金錢是慢慢流向那些願意儲蓄的人。
每月至少存入十分之一的錢,久而久之可以累積成一筆可觀的資產。
金錢的第二定律:
金錢願意為懂得運用它的人工作。
那些願意打開心胸,聽取專業的意見,將金錢放在穩當的生利投資上,讓錢滾錢,利滾利,將會源源不斷創造財富。
金錢的第三定律:
金錢會留在懂得保護它的人身邊。
重視時間報酬的意義,耐心謹慎的維護它的財富,讓它持續增值,而不貪圖暴利。
金錢的第四定律:
金錢會從那些不懂得管理的人身邊溜走。.對於擁有金錢而不善經營的人,一眼望去,四處都有投資獲利的機會,事實上卻處處隱藏陷阱,由於錯誤的判斷,它們常會損失金錢。
金錢的第五定律:
金錢會從那些渴望獲得暴利的人身邊溜走。
金錢的投資報酬有一定的回收,渴望投資獲得暴利的人常被愚弄,因而失去金錢。缺乏經驗或外行,是造成投資損失的最主要原因。
Disposal of SCOMMIR
 Lalala... Disposed all my SCOMMIR last week!!! wakakakaa...
I had been extremely quiet in the blog since couple of months bc.. well, busy will work actually and work until no day no night, not a good life actually... haha
>>>>>
5.5億售印尼海事業務‧史格米海事變現金公司
大馬財經 2010-07-13 10:47
(吉隆坡)史格米海事(SCOMIMR, 7045, 主板貿服組)將透過集團整合活動,脫售核心的海事業務,變成純現金公司,未來業務方向暫時未明。 這間公司發表文告說,旗下兩家獨資子公司,即史格米海事服務和Grundtvig海事,建議以1億7180萬美元(約馬幣5億5000萬令吉),脫售5家間接子公司給80.54%印尼子公司PTRig Tenders(PTRT)。
PTRT將透過銀行貸款和發行附加股籌資展開收購。
惟作為PTRT股東的史格米海事服務,不會認購這批附加股,由一家匿名私人管理基金設立的特別用途公司左玄離岸公司(Portside Offshore Inc.),將收購和轉換這批附加股,以成為PTRT的大股東。PTRT的估值約為2億4630萬美元。這項計劃需待左玄離岸公司先進行精密審核再做決定。 一旦完成,史格米海事持有PTRT股權將沖淡至20.63至24.55%,轉為純現金公司,可能面對停牌的命運。不過,史格米海事考慮收購或注入新業務、或展開聯營公司等,以維持上市地位。惟目前董事部尚未做出任何決定。
這間公司總裁穆尼占表示,與印尼基金探討合作商機符合策略性與時機。由於印尼煤炭生產領域持續擴展,海事務流服務需求不斷提高,加上競爭激烈,因此透過聯營可擴大印尼油輪業務。 他指出,希望能引進左玄離岸公司成為策略投資者後,結合雙方能力與網絡,以擴大PTRT營運能力,這間公司未來仍會參與管理活動。
上週五(7月9日)早市起停牌的史格米海事,將於週二(7月13日)復牌。
<<<<<
Well well well, this trigger me to dispose my SCOMMIR on hand, profit taken around ~18%,
Indead, it is a good news for SCOMMIR to clear up the liabilities and this is a good time for them to avoid the new tighter financing control by Indonasia gov on foriengn sea transportation service provider company.
My concern is more on company future direction.
As i don't know how the board is going to use the cash on hand, so i rather pull out and look 1st. Since now everybody is buying, soon we will know what they are going to do.
My next plan, if price drop back to <49sen, will try to buy in some else will keep the capital for another potential counter :)
Overall, this yr looks like not a good yr for me as most of my pick is stil in negative position. well.. lets wait la..
Subscribe to:
Posts (Atom)


