Monday, August 13, 2018

Weekly Review - 0812

The main activity for this week is to dispo my Asian Pay Tv. It is sad but is a must do with the reason that i shared in my previous post. After i dispo the Asian Pay Tv, i quickly SWAP to some other stock. Fajar and Malton are the 2 stocks that quickly take up my capital from the disposition of Asian Pay Tv. Why Fajar and Malton? first of all, this 2 counters were mentioned in the "Rainmakers", well, thanks to the page and i stretch a bit to check out the feasibility to invest in this 2 counters. Together, i put in a fundamental comparison with Ekovest, Destini and WCT as well. Again, the goal is to look for Malaysia MID CAP developers who have good fundamental, good earning capability and reasonable dividend pay out.


Above data captured from 7th Aug (all except Ekovest) to 13 Aug (Ekovest) through investing.com. can see that Fajar and Malton are the top 2. Based on market CAP, WCT is not really the same batch with the rest and i put it in just as a refferance since it is one of my closely monitored counter.

Fajar have a mix business with additional income from Timber, so to be honest, by putting Fajar in the list to compare is really not an apple 2 apple comparison but rather orange and Mandarin orange comparison. As for Malton, it comes with the honer from Pavilion and some good project on hand is definitely some positive point for it. another key reason for selecting this 2 is, they both have the top 2 highest dividend payout based on current price. In view of their trend, both had kind of recover from bottom with >10% recovery liao, enter at this point will be more comfortable for me since the trend shows recovery and not batting on the re bounce.

Fajar
 
 Malton

For the strategy, the capital from Asia Pay Tv will be divided into 2 and invested in Fajar and Malton @ the price of RM 0.495 and RM 0.655 respectively. Any cut loss? based on the trend and EMA, Fajar should cut at 0.485 while Malton should cut at 0.61, anyway, I'm not so certain about the cut loss price at this moment since the Fundamental for this 2 counters are reasonable to hold for mid to long term with current enter price. Both counter will have their quarter result published in Aug'18, so lets see how it goes.
 
Below is my updated portfolio:
 
Key Notes:
  1. Swap from Asia Pay Tv to Fajar and Malton, loss of ~26$ from Asian Pay Tv :(
  2. Singtel reported their latest Quarter result on 8th Aug with drop in revenue, share price impacted immediately since 10th Aug.
  3. Hanwell reported their latest Quarter result on 13th Aug, which is higher than Q2'17, today is the first day the share price reflected the good news. 


Wednesday, August 8, 2018

The TOP 10 Distinctions Between Millionaires and The Middle Class. Keith Cameron Smith


顾名思义,本书着重于讲解有钱人于普通人的十种习惯差异:
  1. 衡量财富的时间轴,有钱人在乎一年可赚多少;薪水族计较一个月领多少薪水
  2. 有钱人谈观念;薪水族聊是非
  3. 有钱人乐于改变;薪水族抗拒改变,这里讲的是持续性的
  4. 有钱人乐于冒险及精算得失;薪水族害怕离开舒适圈
  5. 有钱人不断学习;薪水族在毕业后就不愿学习。我认为这里的learning指的是所有事情,而不是单一的专业领域
  6. 有钱人掌握时机赚钱,薪水族希望安稳领月薪
  7. 有钱人做钱的主人,乐于分享不计较;薪水族为钱工作,分毫计算怕吃亏
  8. 有钱人慷慨不亲力亲为,拥有消极收入;薪水族吝啬靠自己,着重于积极收入
  9. 有钱人专注于全部财产的增加;薪水族只关心工资涨幅有多少
  10. 有钱人习惯往好方向思考,进入好循环;薪水族经常朝坏方面抱怨,陷入恶循环
这本书讲的都是概念,并不是每个人都能吸收。习惯10,9和2对我来说算是相对比较新的看法,其他的大致上对比市面上的理财书籍没太大惊喜。

Tuesday, August 7, 2018

A Review on Asian Pay Television Trust


APPTV just announced their latest quarter report, such a disapointed result. Infact, it is not totally unexpected, this is what capture from the latest Q-report end 30 Jun 2018:

In constant Taiwan dollars (“NT$”), revenue down 4.1% for the quarter and 4.9% for the half-year as foreign exchange contributed 2.5% negative variance for the quarter and 1.8% for the half-year
  • Basic Cable TV: Down 4.6% for the quarter and 5.6% for the half-year in constant NT$ terms mainly due to lower subscription revenue, driven by marginally lower number of subscribers and ARPU compared to the pcp, and lower revenue generated from channel leasing partially offset by higher airtime advertising sales.
  • Premium Digital Cable TV: Down 10.4% for the quarter and 9.2% for the half-year in constant NT$ terms. Generated predominantly from TBC’s average Premium digital cable TV RGUs each contributing an ARPU of NT$133 per month during the quarter for Premium digital cable TV packages, bundled DVR or DVR-only services.
  • Broadband: Up marginally for the quarter and remained broadly unchanged for the half-year in constant NT$ terms. Generated predominantly from TBC’s average Broadband RGUs each contributing an ARPU of NT$439 per month during the quarter for high-speed Broadband services.
Total operating expenses: Lower operating expenses, mainly due to lower broadcast and production costs, staff costs and other operating expenses.

Below table tell a better story:
In short, the game still on with increase RGUs in Premium digital cable TV but hidden rock shows ARPU for both of the so call potential savior for APTV is not making and real income (claim to be due to spending for promotions and discounted bundled packages that were offered to generate new RGUs and to retain existing RGUs.

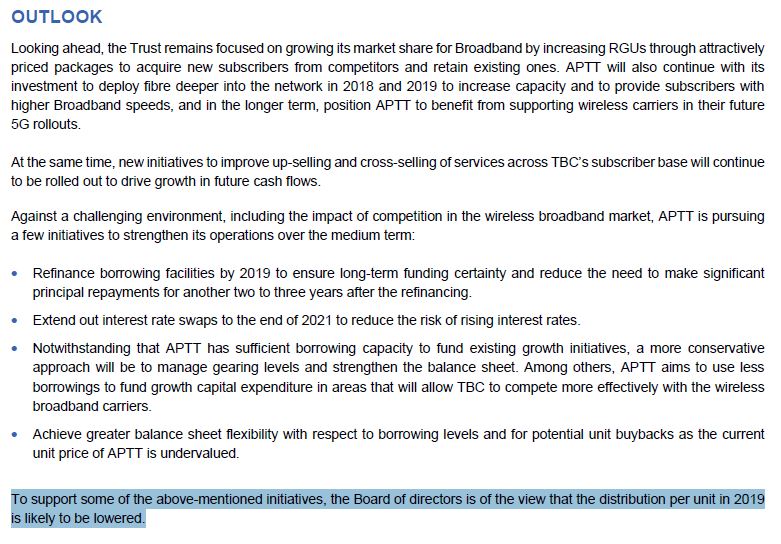
A sad part from the report is below highlighted statment were spotted in the Outlook statement:

==> To support some of the above-mentioned initiatives, the Board of directors is of the view that the distribution per unit in 2019 is likely to be lowered.

My intepretations:
1. The situation is bad, management have no confident to recover the weak performance.
2. DPU lower always not a good thing for me.

A side thought: Do youconfident that APTv can recover the situations by cutting the DPU and with above plan? It all went back to the business that APTv is doing. With that says, i had decided to cut loss at this point, sold off all i have @ 0.40 and take the loss of ~26%. A simple reason, APTv have no longer meet my needs as the future DPU is not secure, so just cut and move on.

I had swap to some Malaysia construction counter. update in next blogging. 

Wednesday, August 1, 2018

Warren Buffett's Ground Rules: Words of Wisdom from the Partnership Letters of the World's Greatest Investor -- by Jeremy Miller


书名有够长的咯。个人觉得这是一本很不错的书,无可否任,巴非特的热门书籍一大堆,著名的有 “巴非特致股东们的信”,“滚雪球”等等,而这本对我来说就好比巴非特投资前传,来看看里面写什么。

此书分为三部;基本概念,投资策略,及心里偏误。作者基本上是把早期巴非特出道时写给“合伙人”的信重新整理了一遍再把大纲分成以上三部来解读。其实,个人觉得比较relevent 的就是基本概念和投资策略。

在基本概念这一章里,不用多说,巴非特的基本投资概念大家都略知一二,本章比较有趣的是巴非特的绩效衡量,他唯一想打败的是DOW,而我一直都在看个人回筹率而已,当然,要效仿他的话,你的投资肯定要是长线的,min 3 years.....

再来是投资策略,原来以前巴哥也是炒股起家的,此章解说了有名的cigar butt investing,既是net-net stock。说到net net stock,巴哥以前只考虑net net performance,而大家所了解的价值投资,就是以合理价买入优秀的公司,其实是巴非特后期的投资策略,本章也解释巴非特为何改变策略。除了低估型投资,也看到一些巴非特以前的投资策略,比如套利型投资,控制型投资,及后期的控股型投资。

其他有趣的info比如如何计算公司价值,及对长线的看法等等都是有比较独特的见解。看了之后,我不敢肯定你的投资会从此无往不利,但是你肯定会对你所了解的巴非特有不同的见解。

Sunday, July 29, 2018

投资成本


先不说买股票有没有赚,只要你做买卖transection,你就要付佣金了,所以今天心血来潮,想看看我这些年来买股票被投行抽的佣金有多少,就从2012到2018 七月吧。这不包括Contra,是的,我定力不足,时不时会玩Contra。

看到summary了吧?我自己都吓到!!这些是感觉不到的成本!其实,逻辑很奇怪,股市如果我们频密地做买卖,单单被抽的佣金就很可多了,还要自己操做那么高风险的投资产品?
...

有时候你不把东西画出墙是看不到的,好好研究,看定定再买,要不然陪了夫人又折兵啊!

Singtel - 4th Jul'18


Singtel closed at 3.02 yesterday, what a direct flight from ~3.40 to current price. So what drives to this trend? The logic seems works for me, main trigger from May 17: Singtel announced the Q4 and 2018 Final report:
  •  Revenue increased (+4.9%) but the underlying net profit dropped (-7.8%) if exclude the gain from the disposition of NetLink Trust.
  • Revenue increase for all the sector except for the National Phone and International Phone, this 2 consist of a small portion of the revenue @ ~8%, something to note but not big.
  • Operation profit dropped mainly from the result of a decline in Airtel’s India earnings and charges from increased network investments and spectrum.
  • 2018 total Div payout is ~81% (include all the special div). This is good for 2018 but no longer for future where by the Div payout will be fixed at 17.5ct for the next 2 FY. Resume the 60-75% Div payout only by FY21.
  • Expect stable “single digit” profit for next 2 years before Singtel can see anything increase in the profit.
Recent share buyback (actually very tiny if compare to the overall all Cap size of SingTel.):
  • May 17: SGD ~1 mil @ SGD3.42/3.43
  • May28: SGD ~ 0.44mil @ SGD 3.34
Risk:
  • Increase of compaction in Singapore telco market with new players coming in end of this year.
  • India Telco join venture is facing hard fight with new competitor.
  • Invrstment cost.
What Singtel is doing so far (According to the latest annual report):
  • Singtel embarked on a company-wide digital transformation more than five years ago to rebuild our business around data and digital. As digital eroded industry barriers and disrupted old business models, going digital has meant developing strategies that go beyond the context of our telco industry. Instead, we have leveraged our telco assets and customer relationships to develop new businesses such as cyber security, digital marketing and smart city solutions. We have also begun building a digital ecosystem with our associates to aggregate millions of customers across the region. As digital
  • Had revolutionized consumer behavior and company processes, we have also digitalised our core consumer and enterprise businesses.
  • Our new growth initiatives have grown from strength to strength – our digital and ICT businesses now contribute nearly 25% of Group revenue.
The reason i buy in:
  • Share price @ 52 weeks low (S$3.4 at that point of time)
  • Good div pay out and stable track record
  • Singapore blue chip
  • Regional dai kor for Telco
  • Sound solid management (based on the road map and transform seen on Singtel)
Any changes against my reason of purchase?
  • Share price @ 52 weeks low -> No, now even lower... haha
  • Good div pay out and stable track record -> announced fix DY for 17.5ct for next 2 FY and resume in FY21, still acceptable to me.
  • Singapore blue chip -> No change
  • Regional dai kor for Telco -> No change
  • Sound solid management (based on the road map and transform seen on Singtel) -> No key person changes
Conclusion:
  • Hold at this moment in view of Div payout in Aug.
  • Expect small re-bounce after reason heavy sell.
- Temporary have no plan to top up, lets see the share price movement in this few days as well as after the Annual GM on 7/24.

Holding (11th June 2018) - *Throwback

Capital Distribution:
  • 1% Cash
  • 97% Share in SGX
    • 42% in 1 high pay Reit (13.8% DPU)
    • 55% in 2 different Companies
  • Annual div payout based on current PF is ~6.2%.
 Since the first review on 15th May, i had made some changes to my portfolio, the main reason behind is to streamline my portfolio and focus on fewer counter that i'm confident with.

1. Asian Pay Tv:

 I had made a transaction to average down this reit at 0.46c, of cause, that is before it went down to ~0.41c and now come back at weaker momentum. My current avg price is at 0.54c with paper loss of ~19%. To be honest, the situation is ugly, i have to admit that, i'm only looking at the high DPU of this counter (~12.2% at my avg price), other than that, the situations of the company are not that attractive with the high gearing and challenging business environment. 2 key challenges for the company are: the popularity of internet Tv in the future over current cable Tv, and the tax rule changes at Taiwan (increase from 17% to 20% for related business), which had significantly impacted the profit of the company.

Well, the situation is still in mix, as the company have an advantage of 100% owning the hybrid fibre coaxial cable network in their franchise areas of Taiwan (Taoyuan, Hsinchu, Miaoli, TaiZhong), owning this facility have add advantage to the company in the sense of:
  • Building the Fibre cable is a resilient business with high barriers of entry due to high network roll out requirements.
  • Large customer base makes TBC attractive to local content providers; unique commercial arrangement with content providers.
  • Long standing relationship with subscribers; deep understanding of Taiwanese viewers’preference.
 How i look at the situation is: although there will be a hard fight between internet Tv and cable Tv, the high quality internet will need to rely on the broadband, which is backed-up by the hybrid fibre coaxial cable network. So, with regards how bad the fight is, Asian Pay Tv should also get some return from their cable network. A good news is that the broadband business is the only business that seeing growth in the latest quarter, which at least re-leaf my short term worried on this counter.

2. Avi-tech.
 I disposed all my Avi with several reasons:
  • Wth the same DPU at ~5%, Singtel seems to be having more advantage in terms of the share price and the business model.
  • I entered Avi without much advantage of the share price, and the latest Quarter report shows decline in the profit, indicates by the weaker demand of electronic testing. So cutting out this counter at 9% loss and work it out as per the plan.
3. Singtel

 No doubt, Singtel share price declined after they announce the latest quarter report due to the profit are not meeting the market expectation. With the original plan to avrg down at 3.2-3.3 and cut loss at 3.0, i had top up some units at 3.29 (after seeing recovery from 3.24), unfortunately, the share price went back down again recently to 3.23. My average price is now at 3.4 (~5% paper loss), but i have no worried about this counter at all: a blue-chip with share price @ 52 wk low + 5% DPU + good management + Temasek holding... hahaha... This will be my long term game.

4. Hanwell

This is really a boring counter, but i had decided to top up more at 0.23c, it is at net net stock at this price. The company have 2 key businesses: A good growth sector from their paper packaging business, and a stable + solid business sector from their FMCG (rice, toufu, snack and bla bla bla....). There is a lot of potential for the share price, and relatively lower risk due to the good FA.
That is all for the changes in my portfolio, now i have a high DPU Reit (relatively high risk ), a superb bluechip stock and a low risk net net stock, i'm very comfortable with the arrangement. I guess the missing type of counter in my portfolio will be a high growth mid cap stock. lets reserving bullet while continue searching for my last piece of puzzle!